Books · 05
Books that keep themselves.
Every shipment, invoice, bill, payment, count and work order posts its double entry the moment it happens. No month-end re-keying, no stitched spreadsheets, and the trial balance balances because it has to.
Start your free 30-day trialHow setting up works
On every plan CoreGrowthScale Pricing
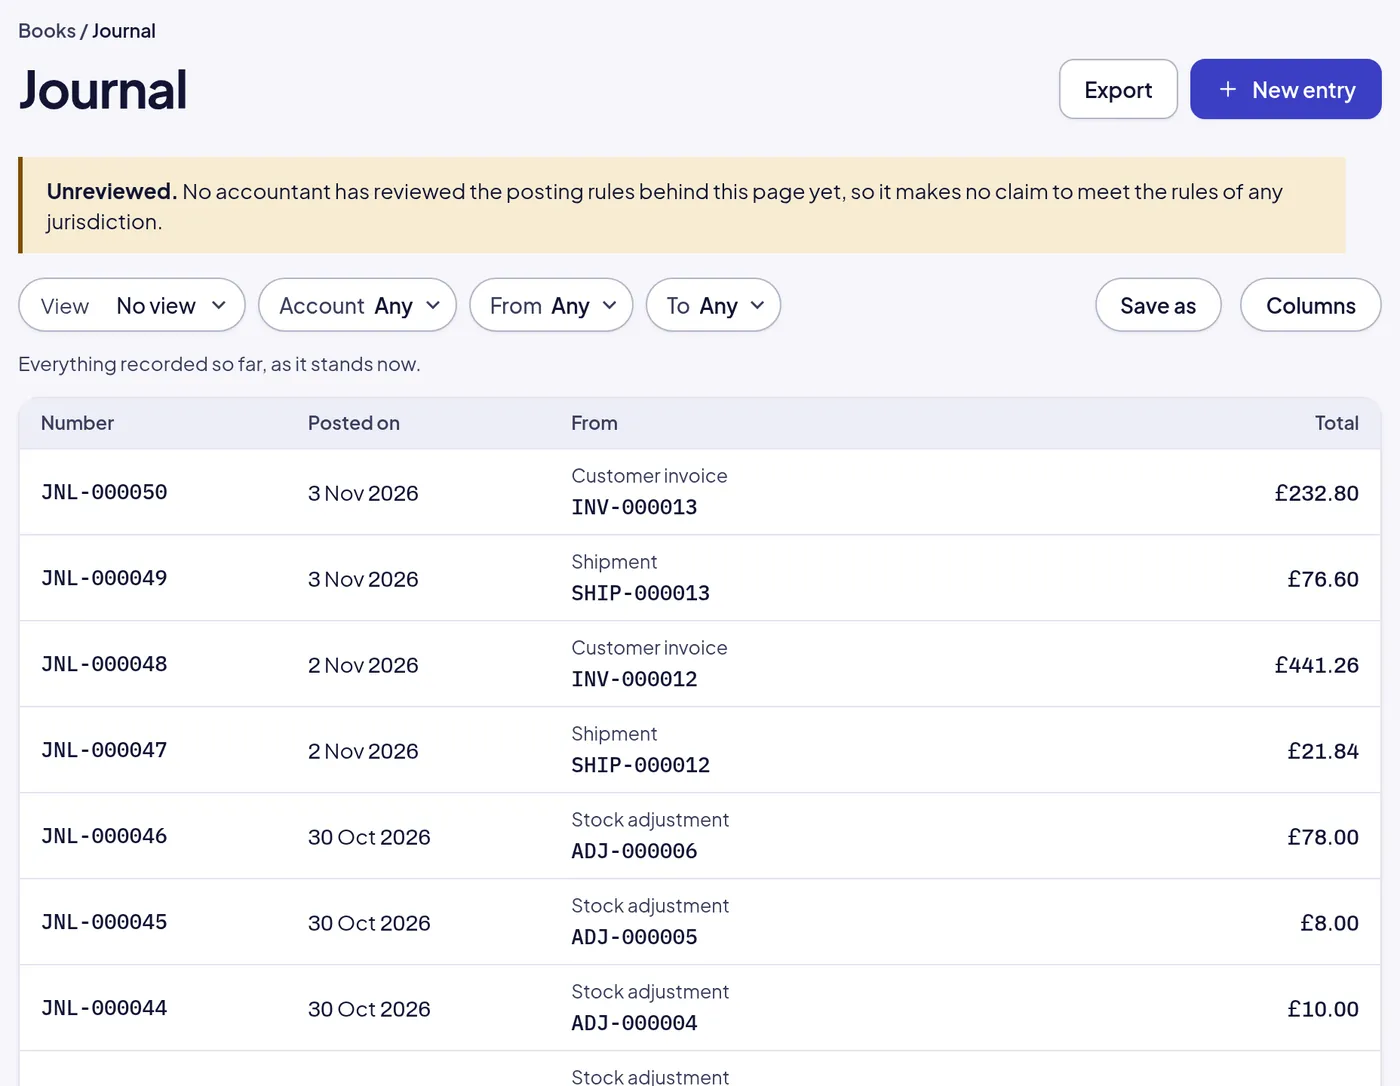
One entry
Posted by the document, not by a person.
Each kind of document posts a fixed pattern of debits and credits. Open the entry and it names the document; open the document and it names the entry.
- SHIP-000013
A shipment
Cost of goods sold against stock, at what the items cost, first in first out.
Dr cost of goods · Cr stock
- INV-000013
A customer invoice
Sales and the VAT on it against what the customer owes you.
Dr receivables · Cr sales, VAT
- BILL-000004
A supplier bill
Purchases or stock and the VAT on it against what you owe the supplier.
Dr purchases, VAT · Cr payables
- PAY-000007
A payment
The bank against the invoice or bill it settles, in full or in part.
Dr bank · Cr receivables
- ADJ-000006
A count or adjustment
The value of what differs from the books, written off or found.
Dr adjustments · Cr stock
The books a growing firm needs to keep.
Enough to run the company and hand a clean set to your accountant, without pretending to be an accounts package for a large one.
- Journal
The journal
Every entry, in order, from the document that made it. Entries of your own for what no document covers. Nothing is ever deleted; a mistake is reversed by its pair.
- Accounts
A chart of accounts
Starts with a sensible chart for a UK firm. Add, rename and reorder accounts, and budget by them.
- VAT
VAT by tax code
Standard, reduced, zero and exempt, set on each item and used on every invoice and bill, so the VAT accounts carry the right amounts.
- Periods
Periods you can close
Close a month or a year so nothing posts into it again, and the figures you gave your accountant stay the figures.
- Statements
Profit and loss, balance sheet, trial balance
Between any two days, or on any day, read on the screen or downloaded as a file.
- Ageing
Receivables and payables, aged
What customers owe you and what you owe suppliers, by how old, with each customer’s statement ready to send.
- Budgets
Budgets by account and month
What each income and expense account should make or spend, month by month, against what the books hold to date.
- Forecast
A cash forecast, eight weeks
Where the bank is headed from the invoices and bills still owed, week by week, with the lowest point ahead.
- Dashboard
The books dashboard
Profit, income and expenses for each of the last twelve months, the bank at each month’s end, and what is owed both ways.
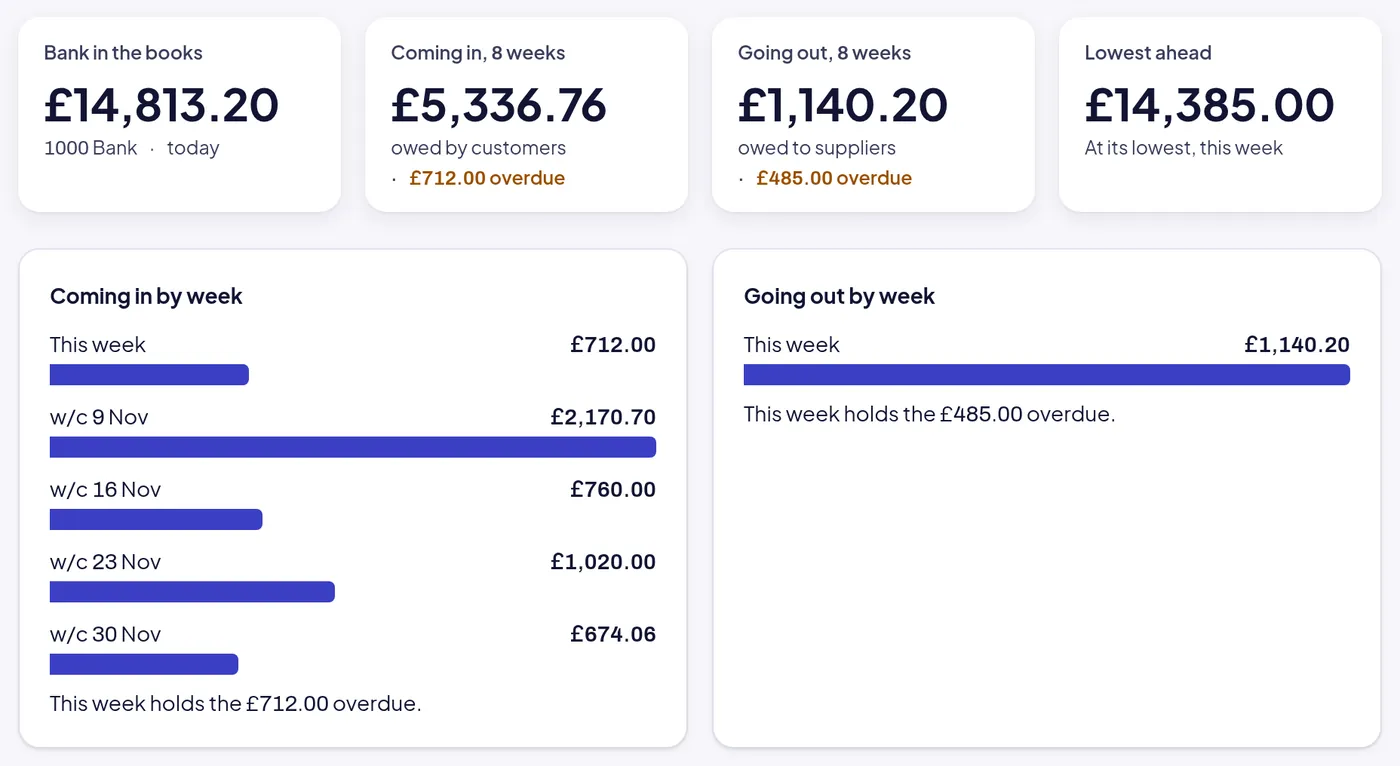
The cash forecast
Where the bank is headed, week by week.
From the invoices and bills still owed, the next eight weeks of money in and out, and the lowest the bank will go. Overdue amounts sit in this week, where they belong.
Where it leads.
The books are the other side of every document in the system. There is no import from sales into the books, because they are already there.
- 01 Sales
Sales post themselves
Shipments post cost of goods, invoices post sales and VAT, payments post to the bank, credits and refunds post their reversals.
- 02 Purchasing
Bills and payments too
A bill posts purchases and VAT the day it is entered; the payment posts from the bank the day it is made.
- 06 Reports and Today
Every statement as a file
The profit and loss, balance sheet, trial balance, ageing and valuation each download for your accountant.
Not built yet
- Bank feeds and reconciliation against the bank’s own statement
- VAT return filing to HMRC
- Payroll, fixed assets and depreciation
- More than one currency
The bank in the books is what the books hold, not a balance read from the bank. No accountant has reviewed the posting rules yet, and the books say so on their own pages; your accountant works from the files they download.
Start here
Read the trial balance in the sample company.
Fifty journal entries from eight weeks of trading, a balance sheet that balances and a cash forecast with an overdue bill in it. Open it and follow one entry back to its document.
Start your free 30-day trial or WhatsApp us
- Emailhello@opsmavix.comAnswered the next working day
- Phone+44 7533 464865On Scale, or to ask before you start
- WhatsAppMessage usThe quickest way to a person